A compliance window for genuine past omissions
A foreign bank account opened during an overseas assignment, shares received under an employee stock plan, an overseas retirement account, a foreign mutual fund or a property retained after returning to India can all create Indian reporting questions. In many cases, the asset itself was acquired from legitimate earnings, but the taxpayer did not understand when it had to appear in the Indian return.
The Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 creates a one-time route for eligible taxpayers to regularise specified foreign assets and foreign income. It operates under Chapter IV, sections 130 to 144 of the Finance Act, 2026 and the Foreign Assets of Small Taxpayers–Disclosure Scheme Rules, 2026.
The e-Filing Portal announcement uses the short form FADS 2026, while CBDT's FAQ and some official communications use FAST-DS 2026. Both references relate to the same scheme. What matters is not the abbreviation, but correctly identifying which of the scheme's two disclosure routes applies.
Who should examine the scheme
The scheme deserves immediate review where a taxpayer failed to file a return, omitted a foreign asset or foreign income from a return filed before the scheme commenced, or where the relevant income or asset escaped assessment. Eligibility and the appropriate route depend on residential status, the year of acquisition or earning, the source of funds, earlier tax treatment and subsequent return disclosures.
Present residential status is not the only test. The official FAQ also addresses persons who are presently non-resident or resident but not ordinarily resident, provided the required historical residency conditions are met. A year-by-year residency chart is therefore essential before concluding that a person is eligible or ineligible.
- Returning Indians who continued to hold overseas bank, investment or retirement accounts
- Employees who received foreign shares, ESOPs or restricted stock units
- Students and professionals who opened accounts while studying or working abroad
- Residents holding foreign securities, mutual funds, property or financial interests
- Taxpayers who reported the related income but omitted the asset from the applicable foreign-assets schedule
- Taxpayers whose foreign income itself was not offered to tax in India
The first decision: which of the two routes applies
FADS 2026 is not one flat-payment scheme. Section 133 creates two separate categories with different conditions, thresholds and financial consequences. Applying the wrong category can distort both eligibility and the amount payable.
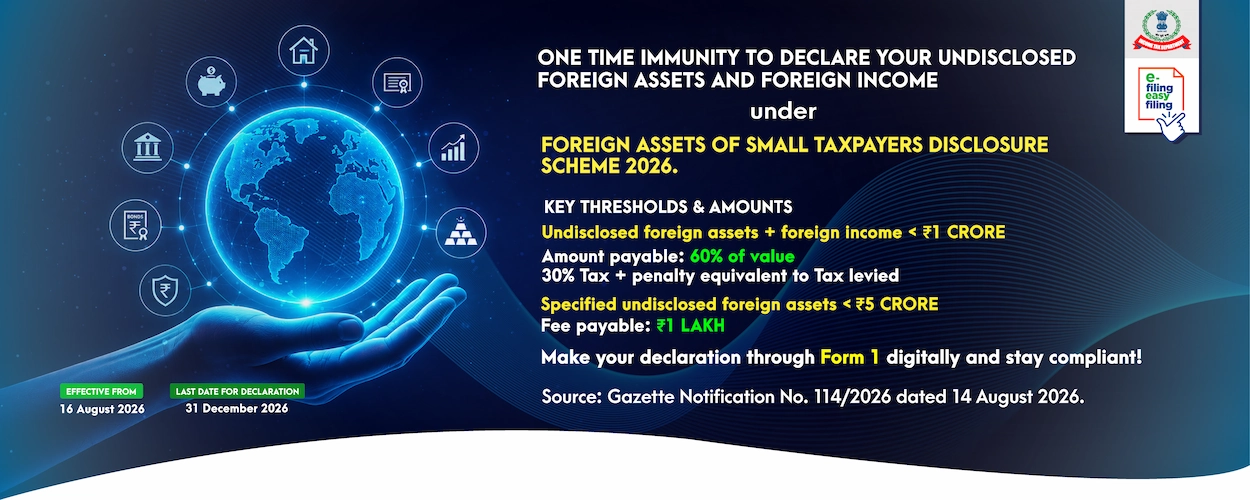
Route 1 concerns an undisclosed foreign asset or foreign income that was chargeable in India but not offered to tax. The combined value of the covered foreign assets, measured on the valuation date, and the undisclosed foreign income must not exceed ₹1 crore. The payment is 30% tax plus an additional amount equal to that tax—an effective total of 60% of the declared value or income.
Route 2 concerns a reporting omission rather than untaxed money: a foreign asset acquired from income already offered to tax, or acquired from foreign income during a non-resident period and later omitted from the relevant schedule after the person became resident. The aggregate value of the covered assets must not exceed ₹5 crore, and the amount payable is a flat fee of ₹1 lakh.
Undisclosed foreign assets plus undisclosed foreign income · effective payment 60%
Already-taxed or qualifying non-resident-period assets · flat fee ₹1 lakh
Why Route 2 does not impose a fee merely because someone was an NRI
The ₹1 lakh route should not be read as creating a reporting obligation for every person while non-resident. The prescribed Form 1 specifically describes the non-resident-acquisition case as an asset acquired from foreign income during the non-resident period but not declared in the relevant schedule of the return on becoming a resident.
Therefore, acquisition of an overseas asset while non-resident is not, by itself, the default being regularised. The relevant omission arises when the person subsequently becomes subject to the applicable Indian foreign-asset reporting requirement and does not disclose the asset in the relevant return schedule.
Residential status can change from year to year, and the reporting position of a non-resident, RNOR and resident and ordinarily resident person is not identical. Before using Route 2, the taxpayer should map the acquisition year, source of funds, year of return to India, residential status for each year and the returns in which Schedule FA or another relevant schedule became applicable.
Key dates and statutory thresholds
The scheme commenced on 16 August 2026. Form 1 must be filed on or before 31 December 2026; the official FAQ states that no declaration can be filed after that date. The valuation date for foreign assets is 31 March 2026.
The ₹1 crore and ₹5 crore limits are eligibility thresholds, not slab rates. If the applicable aggregate exceeds the relevant threshold, the case does not become eligible merely by declaring only part of the asset or income. The full factual position should be established before filing.
- Route 1 threshold: aggregate foreign-asset value plus undisclosed foreign income must not exceed ₹1 crore
- Route 1 payment: 30% tax plus an additional amount equal to the tax—60% in total
- Route 2 threshold: aggregate value of qualifying foreign assets must not exceed ₹5 crore
- Route 2 payment: flat fee of ₹1 lakh
- Valuation date: 31 March 2026
- Last date for Form 1: 31 December 2026
Valuation is more than checking today's account balance
The Rules prescribe asset-specific valuation methods. As a broad principle for several assets, fair market value is the higher of acquisition cost and the price the asset would ordinarily fetch on the valuation date. Where the prescribed market valuation is not carried out, indexed acquisition cost may become relevant. Quoted securities, unquoted shares, immovable property, jewellery, artistic works and interests in foreign entities each require the applicable rule to be checked.
A foreign bank account is especially important: its scheme value is generally based on deposits made from opening of the account up to the valuation date, subject to prescribed exclusions, and not merely the closing balance on 31 March 2026. Re-deposits sourced from withdrawals from the same account are excluded to prevent double counting. The Rules also reduce the value of an old asset or bank account where its proceeds were used to acquire a new asset, again to avoid taxing the same value twice.
All values are reported in Indian rupees. Foreign-currency values must be converted under the prescribed method using the RBI reference rate or the specified cross-currency process as applicable on the valuation date.
How the online filing process works
Form 1 is now enabled on the Income Tax e-Filing Portal. The portal path is: e-File → Income Tax Forms → File Income Tax Forms → Under Other Acts → Foreign Assets of Small Taxpayers Disclosure Scheme, 2026 → Form 1.
Form 1 captures the declarant's details, passport information where applicable, the nature and location of each asset or income item, the relevant year, residential status, valuation and supporting evidence. More than one asset or income item can be included by repeating the relevant fields and annexures.
After electronic verification, the prescribed authority communicates the amount payable through Form 2 within one month from the end of the month in which the declaration is made. Payment is ordinarily due within two months from the end of the month in which Form 2 is received. A further period of up to two months is available with simple interest at 1% for every month or part of a month of delay. Payment is reported with proof through Form 3, after which the authority issues Form 4 certifying the valid declaration and payment.
- Form 1 — declaration and supporting details
- Form 2 — electronic order determining the amount payable
- Form 3 — intimation and proof of payment, including interest where applicable
- Form 4 — order certifying validity and granting the statutory immunity
Declare, value and upload evidence
Authority determines amount payable
Pay and submit proof electronically
Validity and immunity are certified
Documents to assemble before opening Form 1
A declaration should be the result of a reconciliation, not the beginning of one. Form 1 requires documentary support for acquisition of the asset or earning of the income and, where valuation is carried out, the relevant valuation report. A consistent evidence file also reduces the risk of a declaration being challenged as incomplete or materially incorrect.
- Passport history and a year-wise Indian residential-status working
- Indian returns, computation records and relevant foreign-asset schedules for each year
- Foreign bank statements from opening of the account, wherever relevant to valuation
- ESOP, RSU, brokerage, retirement-account and investment statements
- Purchase deeds, contracts, remittance trail and source-of-funds evidence
- Proof that income used for acquisition was already taxed, where Route 2 is considered
- Foreign income, tax-paid and foreign-tax-credit reconciliations
- Valuation reports and exchange-rate workings required by the Rules
What a valid declaration achieves—and what it does not
On a valid declaration and payment, the scheme grants immunity from further tax or penalty and from prosecution under the Black Money Act in respect of the income or asset declared. The declared income or investment in the asset is also protected from being included again in total income under the Income-tax Act or the Black Money Act in the manner provided by the scheme.
The protection is asset- and income-specific. It does not validate an incomplete or false declaration, and it does not provide a general clean chit for matters outside what has been accurately declared. A material false particular or breach of scheme conditions can make the declaration invalid.
The declarant also cannot use the disclosure or amount paid to seek rectification, revision, set-off or relief in relation to a completed assessment. Pending assessment proceedings must take the declaration into account, but the scheme does not reopen every completed tax position in the declarant's favour.
Where the scheme is not available
The official FAQ states that the scheme does not apply to income or an asset representing proceeds of crime where proceedings have been initiated or are pending under the Prevention of Money-laundering Act, 2002. It also excludes income or assets relating to an assessment year for which assessment proceedings have already been completed under the Black Money Act, 2015.
These exclusions should be checked together with the statutory eligibility provisions and the complete procedural history. A taxpayer should not file merely because the monetary threshold is met; the existing notices, assessments and enforcement proceedings must be reviewed first.
Three examples that show the difference
Example 1 — Untaxed asset and income: suppose an undisclosed foreign bank account has a scheme value of ₹60 lakh and undisclosed foreign income is ₹20 lakh. The ₹80 lakh aggregate is within the ₹1 crore Route 1 threshold. Tax at 30% is ₹24 lakh and the additional amount equal to tax is another ₹24 lakh, making the total payment ₹48 lakh.
Example 2 — Asset acquired while non-resident but omitted after becoming resident: suppose a foreign plot acquired from overseas earnings during the non-resident period is valued at ₹3 crore on 31 March 2026. If it was not disclosed in the relevant schedule after the taxpayer became resident and the other conditions are met, Route 2 may apply with a ₹1 lakh fee.
Example 3 — Route 2 threshold exceeded: suppose qualifying foreign mutual-fund units are valued at ₹2.5 crore and foreign quoted securities at ₹4 crore. Their ₹6.5 crore aggregate exceeds the ₹5 crore limit. The taxpayer is not eligible for Route 2 merely by selecting one of the two assets for declaration.
A practical decision checklist before filing
The right starting point is a complete foreign-asset inventory and a residency-and-return timeline. Only after those two records agree should the taxpayer choose Route 1, Route 2 or conclude that the scheme is not applicable.
- List every foreign account, security, retirement interest, property and other financial interest
- Identify legal ownership, beneficial ownership, acquisition date and source of funds
- Determine residential status separately for every relevant year
- Reconcile foreign income with Indian returns, tax payments and foreign-tax-credit claims
- Review when the applicable foreign-asset schedule first became relevant after return to India
- Value each asset under the specific Rule rather than using an approximate current balance
- Aggregate all items before testing the ₹1 crore or ₹5 crore ceiling
- Review existing notices, assessments and proceedings before confirming eligibility
- Prepare the supporting documents and valuation reports before filing Form 1
- File well before 31 December 2026 so that portal or documentation issues do not consume the final days
The opportunity is valuable, but classification must come first
FADS 2026 is a significant one-time compliance opportunity for taxpayers whose foreign holdings or income were not correctly reflected in India. Its most helpful feature is the distinction between untaxed foreign value and a reporting-only omission involving legitimate, taxed or non-resident-period funds.
That distinction must be established with evidence. A foreign asset should not automatically be placed in the ₹1 lakh category merely because the taxpayer believes the funds were legitimate, nor should a reporting-only omission be treated as untaxed income without first tracing the source and tax history.
This article is general professional information based on Chapter IV of the Finance Act, 2026, Notification No. 114/2026, the official FAQ and the portal position checked on 4 September 2026. Residential status, source of funds, asset valuation, return history and pending proceedings should be reviewed before a declaration is filed.